The definitive diligence resource for Main Street acquisitions

Every deal fails for a reason
that diligence would have
caught first.

The Diligence Guide is a free, structured learning resource for acquisition buyers — covering every phase of the due diligence process, from letter of intent to first 90 days post-close.

Free framework & chapters
Paperback and Kindle Editions Available
Live deal services linked
What is due diligence?

The process that determines whether you are buying a business — or a story about one.

Due diligence is the systematic investigation of a business before you commit to purchasing it. It is not a single event — it is a multi-phase process that begins the moment you sign a letter of intent and ends at close.

Most buyers think diligence is about verifying the financials. It is. But it is also about confirming that the operational systems are real, the legal structure is clean, the customers will stay, and the staff won’t quit on day 31.

The Diligence Guide teaches every phase of that process. The book gives you the complete 87-checkpoint framework. The professional services handle it for you when the deal is live and the stakes are too high to do it alone.

The 4 phases of diligence
1

Pre-LOI screening

Evaluate the business from available information before you make a commitment. Ballpark valuation, industry check, initial financial scan. Takes 1–5 hours.

Before LOI
2

Post-LOI financial verification

Full P&L scrutiny, add-back verification, tax return reconciliation, SDE normalization. The most critical phase. 2–4 weeks with professional help.

After LOI
3

Operational, legal & human capital audit

SOPs, contracts, key-man risk, customer concentration, equipment condition, legal compliance. The phase that catches what the financials hide.

After LOI
4

Pre-close finalization

Final document review, representations and warranties, UCC lien search, integration plan. The last protection before money changes hands.

Pre-close

The diligence framework

Four pillars. Every acquisition.

Every business acquisition — from a $300K service route to a $3M platform business — should be evaluated across these four dimensions before close.

💰
01

Financial

Verify the earnings are real. Scrutinize every add-back. Reconcile the P&Ls to the tax returns. Know the verified SDE before you negotiate price.

  • 3-year P&L reconciliation
  • Add-back classification
  • Revenue timing analysis
  • Working capital model
  • Hidden liability detection
Read the chapter
⚙️
02

Operational

Confirm that the business can run without the owner. Document the systems that exist, the gaps that don’t, and the capital required to fix them.

  • SOP completeness audit
  • Software & tooling review
  • Vendor concentration check
  • Equipment condition assessment
  • Owner absence test
Read the chapter
⚖️
03

Legal

Confirm that everything transfers cleanly. Contract assignability, license portability, lien searches, and any litigation that follows the business to new ownership.

  • Customer contract review
  • License transferability
  • UCC lien search guidance
  • Litigation history
  • Lease term assessment
Read the chapter
👥
04

Human & Customer

Map every owner dependency. Identify which staff and customers are likely to leave when the owner does. Score revenue transferability before you close.

  • Owner dependency mapping
  • Key staff retention risk
  • Customer concentration model
  • Revenue transferability score
  • Non-compete structure
Read the chapter

Guide chapters

Work through the guide in order, or jump to where you are.

Each chapter covers one aspect of the due diligence process. The free chapters give you the framework. The book gives you the complete system with scripts, checklists, and templates.

Chapter 01

What is due diligence and why do most buyers skip it?

The four phases of the diligence process, the cost of skipping each one, and the psychological reasons buyers rush past the most important stage of any acquisition.

~15 min readFreeRead now
Chapter 02

How to read a small business P&L like a buyer, not an accountant

The difference between a P&L built for tax purposes and one built for sale. How to identify which line items are real, which are polished, and which are manufactured.

~20 min readFreeRead now
Chapter 03

The add-back problem: how sellers inflate SDE and how to fight back

A full taxonomy of add-back types — legitimate, adjustable, and fraudulent. How to classify each one and rebuild the verified SDE from scratch before you name a price.

~25 min readFreeRead now
Chapter 04

How to reconcile a P&L to a tax return — and why discrepancies kill deals

Every year of P&Ls must be reconciled to the corresponding tax return. This chapter shows you exactly how to do it, what discrepancies to look for, and what each one signals about the seller’s books.

~20 min readFreeRead now
Chapter 05

The 87-checkpoint acquisition audit — complete system

The full 5-pillar, 87-checkpoint framework for conducting a complete pre-close acquisition audit. Every category, every document request, every evaluation criterion — in sequence.

~45 min readIn the bookGet the book
Chapter 06

Seller interview scripts: the questions that reveal what the P&L hides

The specific questions to ask in every seller meeting — about customers, staff, vendors, systems, and the reasons for selling. Including the questions sellers hate most and why you must ask them anyway.

~30 min readIn the bookGet the book
Chapter 07

Negotiating from diligence findings: how to use what you find to reduce the price

How to document every finding with a specific price adjustment recommendation. The negotiation memo format that turns audit findings into LOI renegotiation leverage.

~35 min readIn the bookGet the book
Chapter 08

The 90-day integration playbook: protecting your investment after close

The post-close integration sequence that prevents customer churn, staff attrition, and the operational collapse that destroys acquisition value in the first three months of new ownership.

~30 min readIn the bookGet the book
The red flag encyclopedia

12 accounting tactics Main Street sellers use to inflate earnings

Every one of these has appeared in a real deal reviewed by this team. Some are common. Some are subtle. All of them cost buyers money if they are not caught before close.

Financial manipulation

Pulled-forward revenue

Billing accelerated into the trailing 12 months to inflate the revenue window buyers use for valuation. Invoices sent early, deposits collected for future work, contracts pre-billed.

Critical
Detection signal
Month 11 and 12 revenue spikes vs. same period prior year. Ask for a month-by-month breakdown going back 3 years.
Add-back manipulation

Below-market owner compensation

Owner pays themselves $55K in a role the market values at $95K. The add-back inflates SDE by the stated salary — but the real adjustment is the market rate gap, not zero.

High
Detection signal
Request W-2s and compare owner salary to market rates for their specific role, industry, and geography.
Add-back manipulation

Personal expenses in business accounts

Family vacations billed as “sales trips.” Golf club membership as “marketing.” Personal auto lease as “vehicle expense.” Each one claimed as a legitimate add-back.

High
Detection signal
Request itemized receipts for every marketing and vehicle line item. Look for personal names, family destinations, and non-business vendors.
Related-party transactions

Consulting fees to controlled entities

“Consulting” payments to an LLC owned by the seller’s spouse or sibling. No services documented, no contract, no deliverable. Pure SDE extraction masquerading as an expense.

Critical
Detection signal
Search vendor names against Secretary of State records. Related-party transactions must be disclosed and supported with documentation.
Expense deferral

Deferred maintenance and capital expenditure

Maintenance skipped for 18 months to suppress expenses in the sale window. The P&L looks lean. The new owner inherits a $200K capital call in month two.

High
Detection signal
Request maintenance records for all equipment. Compare current year maintenance expense to prior years. Walk the facilities and equipment in person.
Customer concentration

Single customer above 25% of revenue

One customer representing 30%+ of revenue on a month-to-month contract. The seller calls it “the anchor relationship.” Every sophisticated buyer calls it a single point of failure.

Critical
Detection signal
Request customer revenue report for each of the last 3 years. Build the concentration table yourself — don’t accept the seller’s summary.
Revenue quality

Recurring revenue that isn’t recurring

Project-based revenue classified as “recurring.” Annual contracts that have never renewed. One-time government grants in the baseline. Service agreements with no actual renewal rate.

High
Detection signal
Request the renewal history for every contract in the “recurring” category. A 3-year renewal rate below 80% on “recurring” revenue is a red flag.
Legal risk

Non-assignable customer contracts

The top customer contract has a change-of-control clause. It requires the customer’s consent to transfer. The seller didn’t mention it. The buyer discovers it after close.

Critical
Detection signal
Have your attorney review every material customer contract for assignment provisions. This is non-negotiable before any close above $500K.
Key-man risk

Owner-managed key accounts

The owner personally manages the top 8 customer accounts. No relationship has been transferred to staff. The customers follow the owner when they leave — they don’t follow the business.

Critical
Detection signal
Ask specifically: who is the primary contact for each of your top 10 customers? Are any of those relationships solely with you?
Financial manipulation

Tax return vs. P&L discrepancies

The internal P&L shows $487K SDE. The tax return shows $312K in net income with no explanation for the $175K gap. Buyers who don’t catch this are negotiating on fabricated numbers.

Critical
Detection signal
Build a year-by-year reconciliation table. Every line item that appears in the P&L but not the tax return requires a written explanation and documentation.
Legal risk

Licenses in the owner’s personal name

The business requires a contractor’s license, a pharmacy license, or a professional certification — and it’s registered to the owner personally, not the entity. It doesn’t transfer.

High
Detection signal
Request copies of all licenses, permits, and certifications. Verify each one is in the entity name, not the owner’s personal name.
Hidden obligations

Undisclosed debt and lien obligations

Equipment financing not listed in the liabilities schedule. An SBA loan with a personal guarantee that transfers obligation. UCC filings against business assets not mentioned in the CIM.

High
Detection signal
Run a UCC lien search through the Secretary of State before your LOI deposits are released. Every filing needs to be explained and resolved before close.

The cornerstone resource

The 300-page manual that teaches you everything this guide summarizes.

The free chapters of The Diligence Guide give you the framework. The Due Diligence Bible gives you the complete system — every script, every checklist, every template, and every detailed analysis that turns a framework into a repeatable process.

  • 01The complete 87-checkpoint audit framework used by professional acquirers
  • 02Verbatim seller interview scripts for every phase of the diligence process
  • 03Add-back classification system with examples from 12 common fraud patterns
  • 04Legal document checklist covering contracts, licenses, leases, and UCC filings
  • 05Negotiation memo template that turns findings into price adjustments
  • 06The 90-day post-close integration playbook for protecting your investment
Buy the Book

When the deal is live

Have a specific deal? The guide becomes a professional service.

The Diligence Guide teaches you the framework. When you have a live deal and the stakes are too high to do it yourself, the Buy Scale Sell team handles it professionally.

🔍
Financial verification

Earnings Verified

From $795
$795 diagnostic credited toward QoE
Fast, financial-focused verification. P&L scrub, add-back analysis, and QoE report. Ideal for deals in the $300K–$1M range where financial verification is the primary risk.
  • ✓
    $795 red flag diagnostic call
  • ✓
    QoE report — $4,500
  • ✓
    Available within 48 hours
  • ✓
    Lender-grade earnings summary
Visit Earnings Verified
📊
Business valuation

Buy Scale Sell

$1,499
One-time fee · Instant access
After your diligence confirms the deal is clean, get a data-backed valuation benchmarked against 30M+ comparable transactions. The number that tells you whether the price is right.
  • ✓
    30M+ comparable transactions
  • ✓
    SDE multiple benchmarking
  • ✓
    Lender-ready summary page
  • ✓
    30-day money-back guarantee
Visit Buy Scale Sell
Not sure which service fits? Start at Buy Scale Sell — they will point you to the right resource for your deal.

Diligence glossary

The terms every acquisition buyer needs to understand

A reference guide to the language of small business acquisition — from add-backs to working capital, LOI to QoE. Bookmark this page.

Add-back
An expense added back to net income to calculate Seller’s Discretionary Earnings (SDE). Legitimate add-backs include owner compensation, non-recurring expenses, and personal benefits paid through the business. They must be documented with primary source evidence to be defensible.
See also: SDE, Quality of Earnings
Seller’s Discretionary Earnings (SDE)
The total financial benefit an owner-operator receives from a business, including net profit, owner compensation, and legitimate personal expenses run through the business. SDE is the primary earnings metric for valuing small businesses. It differs from EBITDA (which assumes a management salary) because it starts with the owner’s total economic benefit.
See also: Add-back, EBITDA
Quality of Earnings (QoE)
A financial report produced by a credentialed analyst that verifies a business’s stated earnings against source documents. A QoE confirms the SDE calculation, scrutinizes every add-back, reconciles P&Ls to tax returns, and produces a lender-grade earnings summary. Required by most SBA lenders on deals above $750K.
See also: SDE, Due Diligence
Letter of Intent (LOI)
A non-binding document that establishes the proposed terms of an acquisition — price, structure, exclusivity period, and key conditions. The LOI is not a commitment to a final price, but it anchors the negotiation. Diligence findings discovered after LOI are typically used to renegotiate the price, not to void the agreement.
See also: Due Diligence, Purchase Agreement
Revenue concentration risk
The risk that a disproportionate percentage of revenue is dependent on a single customer. A customer representing 20%+ of revenue is a material concentration risk. Above 30%, most lenders will require additional representations, warranties, or earnout structures. The risk multiplies significantly if the contract is month-to-month.
See also: Key-man risk, Due Diligence
Key-man risk
The risk that the departure of a single individual — typically the owner or a key employee — will materially damage the business. In acquisition diligence, key-man risk is evaluated for both the seller (do customers follow the owner?) and staff (who leaving would cause operational or revenue disruption?). High key-man risk typically requires an earnout or extended seller involvement agreement.
See also: Owner dependency, Earnout
Working capital
The difference between current assets and current liabilities — essentially the cash available to run day-to-day operations. In acquisition negotiations, working capital is normalized and included in the purchase price calculation. A buyer who does not model working capital requirements can face a payroll shortfall within weeks of close.
See also: DSCR, SBA financing
UCC lien search
A search of Uniform Commercial Code (UCC) filings at the Secretary of State level that reveals any secured claims against the business’s assets. A positive UCC filing means a creditor has a legal claim against specific assets — equipment, inventory, receivables, or sometimes the entire business. All UCC filings must be resolved or disclosed before close.
See also: Due Diligence, Purchase Agreement
The book contains a complete 40-term M&A glossary with definitions, examples, and context. Get The Due Diligence Bible →
Heather Griffith Barber
About Heather

Written by someone who has been on both sides of the table.

Heather Griffith Barber built her first business from scratch at 23, co-founding Utah’s largest vehicle wrap company. Over the years that followed, she sat across from buyers and sellers on hundreds of transactions — and watched the same mistakes repeat themselves every time someone skipped a phase of diligence.

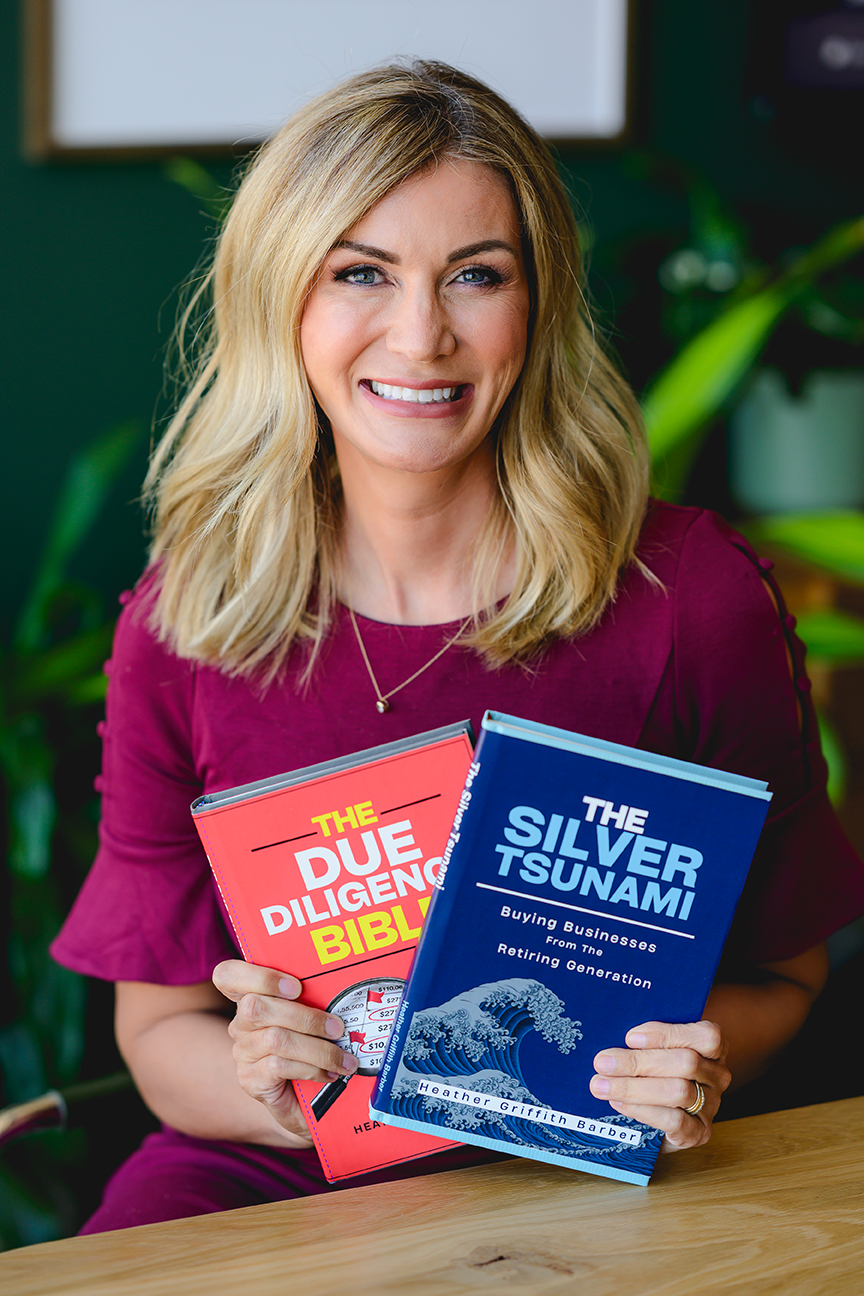
She is the author of The Due Diligence Bible and The Silver Tsunami, the creator of the Buy Scale Sell valuation platform, and the strategist behind the Audit My Acquisition and Earnings Verified professional services. This guide is the free version of the framework she uses with private clients.

900+
Buyers in Buy Scale Sell network
$400M+
In acquisitions reviewed

Reader results

What happened when they used the framework.

First-time buyer — self-service diligence

“I found the guide three weeks before my LOI was set to expire. I ran chapters 2 and 3 myself against the P&Ls and caught $74K in undocumented add-backs in an afternoon. Used that to renegotiate. The guide was free. It saved me $236K.”

TM
Thomas M.
Austin, TX
$236K renegotiated using free chapters
ETA searcher — MBA program referral

“I read the entire guide before I started searching. Understood add-backs before I ever saw a CIM. When the first deal came, I knew exactly what to look for. The book was the best advice I got in the entire 14-month search process.”

AK
Aisha K.
Boston, MA
Closed first acquisition with confidence
Rollup operator — 3rd acquisition prep

“I used the guide before my first deal, the book for my second, and Audit My Acquisition for my third. Each one matched the complexity of the deal. The ecosystem makes sense — it scales with you as the stakes go up.”

RJ
Ryan J.
Denver, CO
Used all three resources across 3 deals
The Buy Scale Sell ecosystem

The Diligence Guide is the starting point. These are the next steps.

Every resource in the Buy Scale Sell ecosystem is designed for a specific stage of the acquisition journey. Start here. Go deeper when the deal demands it.

Common questions

What readers ask before they start.

Is the guide really free?
The framework chapters — what is diligence, how to read a P&L, the add-back problem, how to reconcile financials, and the 12 red flags — are entirely free. The book (available in Paperback and Kindle Editions) contains the complete 87-checkpoint system, all scripts, all templates, and all checklists. The professional services are paid when you have a live deal.
How is this different from EarningsVerified.com and AuditMyAcquisition.com?
The Diligence Guide is an educational resource — it teaches you how to do diligence, understand the framework, and prepare for what to look for before you have a specific deal. EarningsVerified and AuditMyAcquisition are professional services that do the work for you on a live deal. The guide is where you learn the framework. The services are where you apply it when the stakes are high enough to hire someone.
Do I need the book if I read all the free chapters?
The free chapters give you enough to conduct a basic financial review and know what questions to ask. The book gives you the complete 87-checkpoint audit system with verbatim scripts, classified add-back examples, legal document checklists, a negotiation memo template, and the 90-day integration playbook. If you are actively evaluating a real acquisition, the book is essential.
When should I use the professional services instead of doing it myself?
For deals above $500K, use professional services. The ROI is obvious: on a $1M deal at 3.2x, a $50K SDE finding saves $160K at close. The $750 diagnostic call or $9,500 full audit pays for itself many times over on any deal of meaningful size. Below $500K, the book and free guide are often sufficient for a first-time buyer with no time pressure.
What industries does the diligence framework apply to?
The framework was designed around Main Street and lower-middle-market acquisitions: trades businesses, service routes, professional services, retail, healthcare, and franchise concepts. It is not designed for tech, SaaS, or large-market M&A. If your target business has physical operations, employees, and owner-operated financials, this framework applies.
Can the guide be used by a first-time buyer with no M&A background?
Yes — this is the primary audience. Every chapter is written for someone who has never completed an acquisition. Technical terms are defined when introduced. The framework is sequential. The book contains verbatim scripts so you know exactly what to say and ask at every stage. You do not need financial training to use this framework — you need to read it in order before you sign your first LOI.
Start learning. Start protecting yourself.

The best time to learn diligence was before your first deal. The second best time is now.

Start with the free framework. Get the book when you are ready to go deep. Hire the team when the deal is live and the stakes are too high to do it alone.

✓
Free framework  ·  Available in paperback and Kindle editions  ·  Professional services from $795  ·  Powered by Buy Scale Sell